
Hong Kong's Ensemble Pilot Adds 24/7 Tokenized Central Bank Money
Hong Kong's tokenized deposit pilot no longer has to wait for the banking day to end a payment. The Hong Kong Monetary Authority (HKMA) has extended its Ensemble pilot so the interbank settlement leg can now use tokenized central bank money available around the clock, not just the RTGS system during its operating hours. For anyone selecting crypto accounting software to serve banks, corporates or their auditors, the practical message is simple: settlement events can now land at any hour, and your ledger has to treat them as first-class, final entries.
This article sets out what the source reports, why the two-leg structure matters for bookkeeping, and what finance teams, auditors and CFOs should check now. It sticks to what has been published about the pilot. Where the implications for accounting and tax go beyond the reporting, they are analysis, not announced rules.
What the HKMA changed in the Ensemble pilot
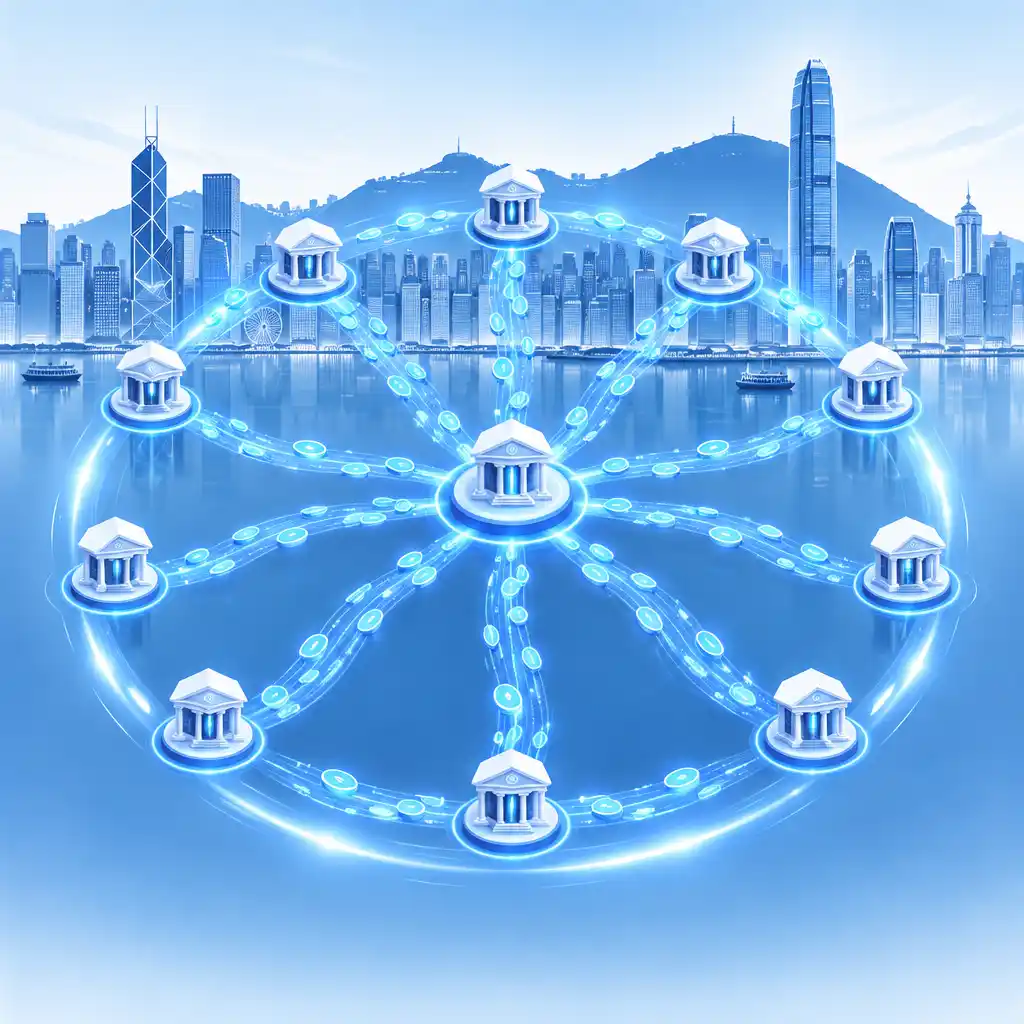
Ensemble is the tokenized deposit pilot run by the HKMA. Until now, the interbank settlement channel in the pilot relied on RTGS, the real-time gross settlement system that operates within set hours. The update adds a second option: tokenized central bank money that is available 24/7. That means the settlement step behind a tokenized deposit payment is no longer tied to the opening hours of the conventional system.
Why a mirrored interbank payment is needed
The reporting explains the logic. A tokenized deposit is a liability of the bank that issued it. Because each participating bank issues its own deposit tokens, a payment between customers of two different banks cannot simply move a token and be done. Every token payment has to be mirrored by an interbank payment, so that the banks settle the underlying obligation between themselves. That mirrored leg is the part that has now moved into tokenized form and is no longer limited to RTGS operating hours.
Put plainly, there are two things happening in one commercial event: the customer-facing movement of a bank deposit token, and the bank-to-bank settlement that backs it. Before this change, the first could in principle be always on while the second had to wait. Now both can run continuously.
Wider participation
The HKMA has also widened the pilot. Participating banks have grown from seven to 12, and other pioneer users have risen from 13 to 20. The source mentions a list of those participants, but it is not reproduced in the excerpt available here, so this article does not name them.
| Pilot element | Before | Now |
|---|---|---|
| Interbank settlement asset | RTGS, within operating hours | Adds tokenized central bank money, available 24/7 |
| Participating banks | 7 | 12 |
| Other pioneer users | 13 | 20 |
Use cases: corporate treasury and tokenized money market funds
The primary use cases in the pilot have been corporate treasury payments made with tokenized deposits, and investment in tokenized money market funds (MMFs). The source adds a relevant market development: just last week, Hong Kong launched regulated trading of tokenized MMFs through one of the local crypto exchanges.
Moving cash into and out of funds
According to the reporting, the combination means corporates can move money into or out of tokenized funds without waiting for the usual subscription and redemption windows. For a treasurer, that changes the cash-management rhythm. Surplus cash could be parked in a tokenized MMF outside traditional hours and drawn back when needed, with the settlement leg also available outside traditional hours.
That is a commercial and operational change, but it is also a recording change. A subscription that settles on a Saturday evening is still a subscription, yet the reporting date, the cut-off treatment and the cash-versus-investment classification all depend on when and how the transaction settled. Finance teams should not assume that weekend or overnight activity will fall neatly into the next business day's batch.
Other central bank initiatives
The source notes that other central banks are enabling tokenized central bank money too, naming Europe's Pontes among them, while cautioning that the cash tokens there are at the minimal viable product phase. The excerpt is garbled on the full list of comparable projects, so it is safest to treat Hong Kong's change as one of several early moves in the same direction, with different levels of maturity, not a settled global standard.
Accounting implications for firms, CFOs and auditors
None of what follows is an announced accounting standard. It is a practitioner's reading of how a 24/7, two-leg settlement model touches the books. The right treatment will depend on your reporting framework, the specific instrument, and your auditor's view.
Recognition, timing and cut-off
Continuous settlement puts pressure on cut-off. If a payment settles at 02:00 on a non-business day, which period and which date does it belong to? Your policy should say whether you use the settlement timestamp, the trade timestamp or a next-business-day convention, and apply it consistently. Auditors testing cut-off will want to see that the policy exists and that the system follows it.
Time zones add a layer. A timestamp in Hong Kong time can fall on a different calendar date in another jurisdiction. Groups that consolidate across regions should settle on a single reference time zone for period-end cut-off and document it.
Two legs, one economic event
Because each token payment is mirrored by an interbank payment, the books should be able to link the two. For a corporate holding tokenized deposits, the asset is a claim on a specific bank, and the instrument sits within that bank's liability. For a bank or other participant handling the interbank leg, the settlement asset is different again. A ledger that stores each leg as an unrelated transaction invites reconciliation breaks, duplicate entries and unexplained differences at month end.
Good digital asset accounting software should let a team tie the customer-facing token movement to its settlement counterpart through a shared reference, and show both on one audit trail. That does not require any special treatment of the tokens themselves. It requires disciplined data, with consistent transaction identifiers, wallet or account mapping, and counterparty tags.
Classification of what you hold
Tokenized deposits, tokenized central bank money and tokenized MMF units are not the same thing, and they should not be lumped together. A deposit token is a bank liability from the holder's side, a claim against the issuing bank. Units in a tokenized MMF are an investment. Whether a given holding qualifies as cash or a cash equivalent is a judgement for the entity and its auditor under the applicable framework, informed by the instrument's terms. The pilot reporting does not settle that question, and this article does not either. What it does show is that a chart of accounts built only for volatile crypto assets will be too blunt for this activity.
What this means for crypto accounting software and bookkeeping tools
The change is a useful test of whether your tooling was designed for blockchain-native activity or merely adapted from end-of-day banking feeds. Teams evaluating crypto bookkeeping software or a broader platform can use the following as a practical checklist.
Questions to put to your tooling
- Does it ingest and timestamp transactions at any hour, with no dependence on a banking-day batch?
- Can it link the two legs of a tokenized deposit payment, the token movement and the interbank settlement, under one reference?
- Can it classify deposit tokens, central bank money tokens and tokenized fund units as separate asset types with their own policies?
- Does it support a defined cut-off rule and a single reporting time zone?
- Can it export a clean audit trail that shows who recorded what, when, and against which source data?
- Does it handle counterparty exposure by issuing bank, since each deposit token is that bank's liability?
Reconciliation and controls
Round-the-clock settlement shortens the window in which exceptions can be caught by a human on the next working morning. Automated reconciliation, alerts for unmatched legs, and clear ownership of exception queues become more important. Segregation of duties still applies: the person who approves a treasury movement should not be the person who clears the reconciliation break for it.
Where the broader context sits
This change fits a broader pattern of Hong Kong tokenization activity. Our earlier coverage of Hong Kong 24/7 tokenized settlement and stablecoin accounting looked at the stablecoin side of the same direction of travel, and our note on the Hong Kong SFC tokenisation push covers the securities regulator's parallel agenda. For a wider view of institutional tokenization and its finance-team consequences, see what finance teams must prepare for as DTCC pushes tokenization. For the compliance reporting foundations that sit under all of this, start with our crypto compliance reporting guide.
Tax and AML considerations to keep on the radar
The source is a market-structure report, not a tax or AML notice, so there are no new tax rules or AML obligations to report from it. Still, several questions follow naturally, and a careful team will flag them early.
Tax questions for corporates
Tax treatment typically follows the legal and economic nature of the instrument and the taxpayer's jurisdiction. A deposit token that represents a bank deposit may be treated very differently from a tokenized fund unit, and the realisation event for a fund redemption may differ from that for a simple deposit transfer. Because corporates can now move into and out of tokenized MMFs outside the usual windows, the date of acquisition and disposal, and the associated gain, income or foreign exchange effects, should be captured precisely. Confirm treatment with your tax adviser in the relevant jurisdiction, and do not assume that the pilot's novelty creates any special relief or exposure.
AML and counterparty diligence
The pilot is run by a central bank with named, regulated participants, which is a different risk profile from permissionless activity. Even so, 24/7 settlement means monitoring cannot rely on a working-hours review cycle. Compliance teams should confirm that transaction monitoring, sanctions screening and escalation procedures cover outside-hours activity, and that records tie each payment to a verified counterparty. Our recent coverage of the FATF October 2026 statements is a reminder that jurisdictional risk lists are updated regularly and should feed into screening rules.
Practical next steps for the next 30 days
For accounting firms and auditors
Ask clients who use tokenized deposits or tokenized MMFs how settlement is recorded, who owns the cut-off policy, and how the two legs are linked. Update audit programs to test outside-hours transactions, and request the instrument terms so classification judgements are documented, not assumed.
For CFOs and treasurers
Review your accounting policy for tokenized instruments, set a reporting time zone and cut-off convention, and confirm that treasury, accounting and compliance agree on one source of truth for settlement timestamps. Check counterparty limits by issuing bank, since each deposit token is a claim on a specific institution.
For finance operations and systems owners
Map your data flows from banks or participants into the ledger. Confirm that your system does not drop or re-date outside-hours entries, that identifiers survive from the customer-facing leg to the settlement leg, and that exception alerts reach a named person at any hour.
What we still don't know
The reporting is brief. It does not describe the technical design of the tokenized central bank money, its legal status, any fees, or how the HKMA intends to move from pilot to production. It also does not say whether the pilot's accounting or regulatory treatment will be addressed by guidance. Treat any claim that goes beyond those published facts with caution, and revisit your assumptions when the HKMA or the participating banks publish more detail.
FAQ
What exactly did the HKMA change in the Ensemble pilot?
It extended the interbank settlement channel so that, in addition to RTGS, it can use tokenized central bank money available 24/7. That mirrored interbank leg is no longer limited to RTGS operating hours.
Why does a tokenized deposit payment need an interbank payment?
Each deposit token is a liability of the bank that issued it. To support payments between customers of different banks, each token payment is mirrored by an interbank payment so the banks settle between themselves.
How big is the pilot now?
Participating banks have grown from seven to 12, and other pioneer users from 13 to 20, according to the reporting.
Does this create new tax or accounting rules?
No new rules were reported. The source is about market infrastructure. Recognition, classification and tax treatment still depend on your reporting framework, the instrument and your jurisdiction, so confirm with your auditor and tax adviser.
What should crypto accounting software be able to do for this activity?
It should record transactions at any hour, link the token movement to its interbank settlement leg, separate deposit tokens, central bank money tokens and fund units as distinct asset types, apply a consistent cut-off rule, and produce a clear audit trail.
Source
Source: Ledger Insights