
DeFi Accounting: What Protocol Mechanics Mean for Your Books
DeFi accounting starts with understanding what the protocol actually does with your assets. The Block's DeFi 201 explainer describes decentralized finance as a connected system of smart contracts, liquidity pools, oracles, governance and composable integrations, and each of those pieces creates transactions that a finance team has to classify, value and reconcile. If your entity trades, lends, supplies liquidity or votes on-chain, the mechanics below are the raw material for your ledger.
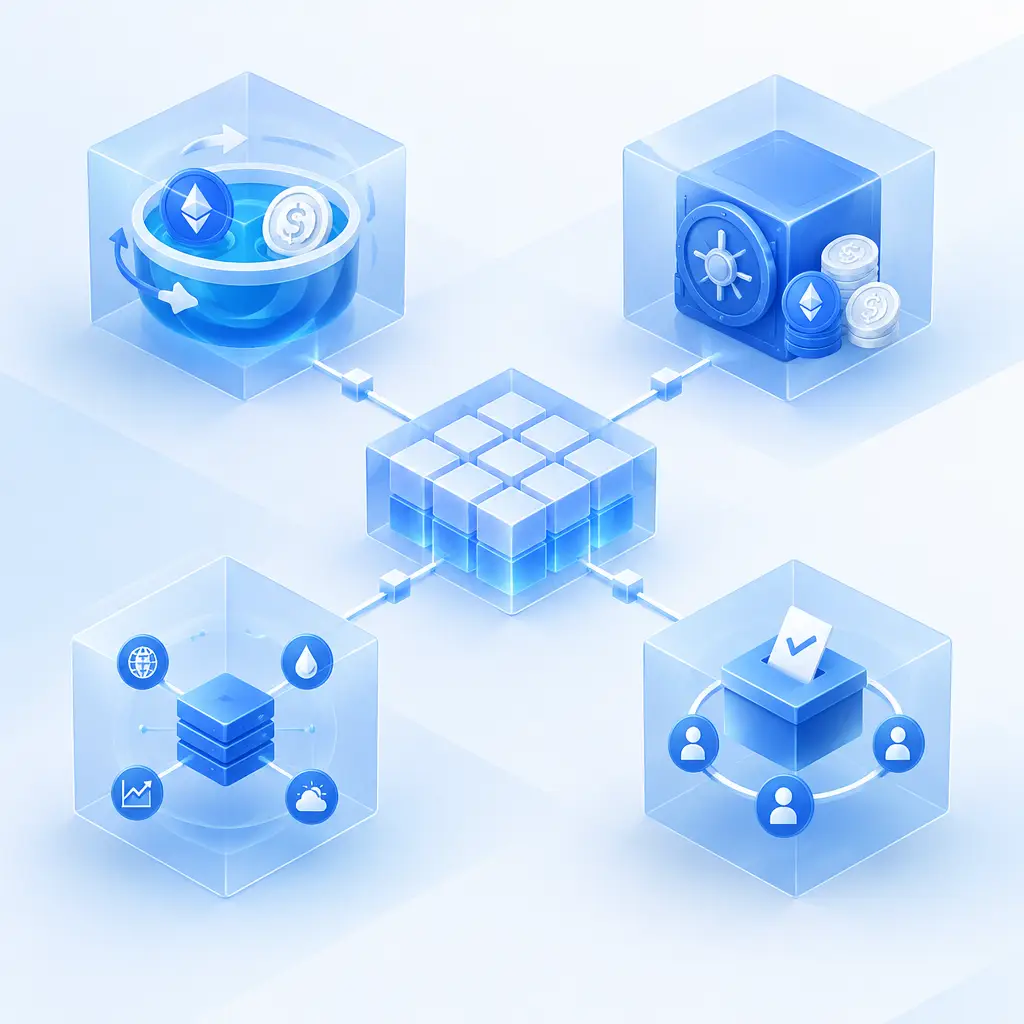
This is an educational explainer, not a regulatory change. It does not announce a new rule, a new standard or a new deadline. Its value for accountants, auditors and CFOs is different: it lays out, in one place, the building blocks of DeFi, and that makes it a useful checklist for deciding whether your crypto accounting software and your bookkeeping procedures capture what happens on-chain. Below, we take the source's own framework and translate it into accounting, tax and control questions.
Why DeFi Is a System, Not a List of Apps
The source makes one framing point that matters for finance teams: DeFi is best understood as a connected protocol system rather than isolated applications. Its main components are decentralized exchanges, lending protocols, yield aggregators, oracles, decentralized derivatives, governance and composability. A single wallet can touch several of them in one afternoon, and the outputs of one protocol often become the inputs of another.
The source is also careful on a conceptual point. DeFi does not remove every kind of intermediation. It changes where coordination happens. Rules that a platform, broker, exchange or bank would normally enforce are instead encoded in smart contracts, governance systems, oracle feeds and liquidity mechanisms. For an accountant, that shift has a practical consequence: there is often no counterparty statement, no broker confirmation and no bank-style account summary. The on-chain record is the primary evidence, and your team has to interpret it.
The common building blocks
Most protocols combine a few elements: users, smart contracts, liquidity providers, traders, borrowers, lenders, governance participants and external data providers. The exact mix depends on the protocol type. When you onboard a new protocol into your processes, identifying which roles your entity plays is the first step. An entity that supplies liquidity has a different set of records, risks and tax questions from one that only swaps tokens or only borrows against collateral.
Why this matters for control design
Because protocols depend on one another, a failure in one can travel. The source notes that dependencies can transmit smart-contract, oracle, collateral, bridge or governance failures across DeFi. That is a risk-management point as much as a technical one, and it is why we would pair any DeFi inventory with a view of enterprise risk management for crypto-active firms. If your books show an asset sitting in a vault, your risk register should also show which protocols, oracles and bridges sit underneath it.
Trading and Liquidity: What Exchanges and Pools Create in Your Records
The source traces the evolution of decentralized exchanges. Early designs borrowed from order books, where buyers and sellers post bids and asks. On-chain order books can be expensive and capital-inefficient because each order update consumes gas and liquidity may sit idle. Automated market makers changed the model: traders do not match with another person's order but trade against a shared liquidity pool supplied by liquidity providers. A liquidity pool is a smart contract that holds tokens, and an algorithmic formula sets prices from the pool's reserves.
Automated market makers and swaps
The constant product model keeps the product of the two token reserves constant, so prices move automatically as traders buy one asset and add another. The source describes the model as simple and resilient, while noting that it spreads liquidity across all possible prices, which can be capital-inefficient. It also lists other designs: concentrated-liquidity, constant-sum and hybrid AMMs, plus intent-based routing by competing solvers.
For bookkeeping, the practical point is that a swap is a disposal of one asset and an acquisition of another, executed against a contract rather than a person. Each swap carries a date, a pair of quantities, a network fee paid in gas and a price implied by the pool. A bookkeeping process that only reads exchange CSV files will miss all of this. Digital asset accounting software has to ingest on-chain transactions directly, including the gas component, and price both legs at the time of execution.
Liquidity provision and what to record
Liquidity providers deposit assets into pools so others can trade, and may earn a share of trading fees. The source stresses that this is not passive income without risk: returns depend on trading volume, fee tiers, price movement, pool design and impermanent loss. From an accounting standpoint, that sentence contains several separate questions your team has to answer.
- What did the entity give up when it deposited assets, and what did it receive in return?
- How are accrued fees recognised, and when are they realised?
- How is the position valued at the reporting date, given that its composition changes as prices move?
- How is impermanent loss reflected, if at all, in the measurement of the position?
The source does not prescribe an accounting treatment, and neither do we here. The treatment depends on your reporting framework, your jurisdiction and your auditor's view. What the explainer does give you is the vocabulary to document the facts: pool design, fee tier, deposit and withdrawal dates and the price movement over the holding period.
Lending, Yield Vaults and Oracles: Where Balance Sheet Questions Multiply
Lending is where DeFi starts to look most like conventional finance, and also where the differences become sharpest for a preparer of financial statements.
Overcollateralized lending
The source explains that DeFi lending protocols let users supply assets to earn yield and borrow against collateral without a traditional bank. Smart contracts replace bilateral lending relationships with pooled markets that set rules, manage collateral and enforce liquidations automatically. A typical protocol uses overcollateralization: a borrower deposits collateral, borrows a smaller value against it and must keep the position healthy. If collateral value falls too far, the protocol can liquidate the position to protect the pool. The course material also covers utilization-based rates, supply and borrow APY, and health factors.
For a finance team, three records matter. First, the collateral posted, which may remain an asset of the entity but be restricted in practice. Second, the borrowed amount and the accruing cost of borrowing, which varies with utilization. Third, any liquidation event, which is a forced disposal on terms set by the protocol. Treasury teams should monitor health factors as a risk indicator and make sure the accounting records can reconstruct a liquidation after the fact.
Yield aggregators and vaults
Yield aggregators route deposits across strategies and automate compounding. Users deposit into a vault, and the aggregator follows a strategy. The source is explicit that this does not remove risk: it adds smart-contract exposure, strategy risk, fee policy, governance risk and dependence on keepers or automation agents. It also makes the point that yield optimization is a mechanism to understand, not a recommendation.
Vaults complicate bookkeeping because the entity may hold a receipt or share token while the underlying assets move between protocols without further action from the user. Your records need to link the receipt token to the underlying deposit and to the strategy, otherwise the balance sheet shows an asset nobody can explain to an auditor.
Oracles and why they are an accounting input
Lending markets need asset prices to value collateral, derivatives need reference prices, synthetic assets need external data and liquidations depend on timely, accurate price information. Oracles supply that data to smart contracts. Because contracts execute automatically on oracle inputs, the source calls oracle design a core security issue: bad, delayed, manipulated or concentrated data can create losses across trading, lending, derivatives and liquidation systems. More resilient designs combine multiple sources and aggregate observations before publishing a value on-chain, which reduces dependence on one provider but does not eliminate latency, source correlation or governance risk.
The accounting parallel is direct. Your own valuation relies on price sources too. If a protocol liquidated a position at an oracle price that differs from the market price your team uses for period-end valuation, you will need to explain the gap. Documenting your pricing policy and the price source for each asset class is the same discipline applied to your side of the ledger.
Derivatives, Governance and Composability: The Hardest Records to Keep
The final cluster in the source is where operational complexity peaks.
Decentralized derivatives
Decentralized derivatives create exposure to assets or market outcomes without necessarily holding the underlying asset. The source names perpetual futures, options, synthetic assets and other collateralized instruments, and lists the key mechanics: collateral, margin, funding rates, liquidation thresholds and protocol risk controls. Perpetual futures have no expiry and use funding payments to keep contract prices aligned with spot prices. Like other DeFi products, derivatives can raise capital efficiency but also introduce leverage, liquidation, oracle and systemic-risk concerns.
Funding payments are recurring cash flows that can run in either direction. A bookkeeping process needs a clear policy for recording them, and a clear method for separating margin collateral from realised and unrealised results on the position.
Governance tokens and treasuries
Many protocols are governed through DAOs, governance tokens, proposals, voting systems, delegation and treasuries. Governance decides how protocols update parameters, allocate incentives, manage upgrades and respond to risk. Proposals may need a quorum before a vote takes effect. The source also flags the downsides: token-weighted voting can give large holders outsized influence, low participation can make decisions fragile and delegation can centralize practical control.
If your entity holds governance tokens, two questions follow. How are those holdings classified and measured? And do voting rights or delegation create any disclosure or related-party consideration for your reporting? Those are judgments for you and your auditor, but the explainer makes clear why the questions arise. Governance outcomes can change protocol parameters that directly affect the yield, risk or availability of assets your entity has deployed.
Composability and layered exposure
The source describes composability as protocols combining like money legos to create new products. That is also how failures propagate: a smart-contract bug, an oracle error, a collateral problem, a bridge failure or a governance decision in one place can reach positions several layers away. For records, this means a single economic position can span several contracts. Each hop may generate its own transaction, fee and receipt token. A good chart of accounts for DeFi activity tracks the position as a whole while preserving the individual on-chain steps that support it.
Enforcement news is a reminder that these systems attract attackers. Readers following the extradition of an alleged Nomad Bridge exploiter will recognise the bridge and smart-contract risks the explainer lists in the abstract.
What Finance Teams and Individual Filers Should Do Next
The explainer is general education and does not discuss any tax rule, so none of what follows is drawn from it as a legal claim. It is our reading of what the mechanics imply for practice.
For firms, CFOs and auditors
- Build a protocol inventory. List every protocol, pool, vault and governance system your entity or your client touches, and tag the mechanics each one uses.
- Map each mechanic to a record. Swaps, fee accruals, deposits and receipt tokens, borrow positions, liquidations, funding payments and governance holdings each need a defined recording policy.
- Document price sources. Because oracles drive on-chain outcomes and your valuation drives the financial statements, write down which price source you use and why, and how you handle differences.
- Test your tooling. Confirm that your crypto bookkeeping software reads on-chain data, captures gas costs and links receipt tokens to underlying positions, rather than relying on exchange-style statements.
- Keep an evidence trail. Because there is no intermediary statement, retain transaction hashes, contract addresses and timestamps as audit support.
For individual filers and the advisers who support them
If you've used a DEX, supplied liquidity, borrowed against collateral or joined a vault, you've probably created more taxable and reportable events than your wallet balance suggests. We'd recommend exporting your full on-chain history for the year and checking that every swap, liquidity deposit and withdrawal, reward and liquidation appears. Tax treatment varies by country and by the specific transaction, so confirm it against your own tax authority's guidance or with a qualified adviser. For a sense of how regulators are thinking about reporting around decentralized venues, see how DEXs could be treated as brokers under Illinois' digital asset tax proposal.
What the source does not tell you
The explainer does not set out regulatory obligations, reporting requirements or accounting standards, and we have not inferred any. It also does not quantify any market size, yield or loss. Treat it as a map of mechanics, then take your jurisdiction's rules and your applicable accounting framework to decide how each mechanic is recorded and reported. For the wider compliance picture, our pillar page on crypto compliance reporting is the right next stop.
FAQ
What is DeFi accounting?
DeFi accounting is the practice of recording, valuing and reporting activity that happens through smart contracts, such as swaps, liquidity provision, lending, borrowing, vault deposits, derivatives and governance holdings. Because there is often no intermediary statement, the on-chain record becomes the main evidence.
Why can't a standard exchange export cover DeFi activity?
DeFi transactions happen between wallets and contracts, not inside a single platform's database. Gas costs, receipt tokens, pool shares and multi-step interactions across protocols won't appear in an exchange-style file, so your tooling needs to read on-chain data directly.
Does the DeFi 201 explainer say how to account for liquidity pool positions?
No. It explains how pools, fees and impermanent loss work, and notes that returns depend on volume, fee tiers, price movement and pool design. The accounting treatment depends on your reporting framework, jurisdiction and auditor, so document the facts and agree the policy with your adviser.
How do oracles affect the books?
Oracles feed prices into lending, derivatives and liquidation logic. If a protocol acts on an oracle price that differs from the source your team uses for valuation, you may need to reconcile the difference. Writing down your own pricing policy makes that explanation much easier.
What should a firm do first when a client uses DeFi?
Build an inventory of the protocols, pools, vaults and governance systems involved, tag the mechanics each one uses and confirm your software captures each category. Then retain transaction hashes, contract addresses and timestamps as the evidence trail.
Source: The Block